How Lukas Haffer Is Using AI to Make Small-Business Lending Faster for American Banks
Small businesses are essential to the US economy, but obtaining a bank loan can still be slow and frustrating. Business owners may need to complete lengthy applications, send financial statements, answer repeated questions, and wait while a lending team reviews the documents.
The process can be difficult for banks as well. Small-business applications often require significant manual work, even when the loan amount is relatively modest. Bank employees must collect missing information, organize documents, review financial records, prepare credit summaries, and communicate with applicants throughout the process.
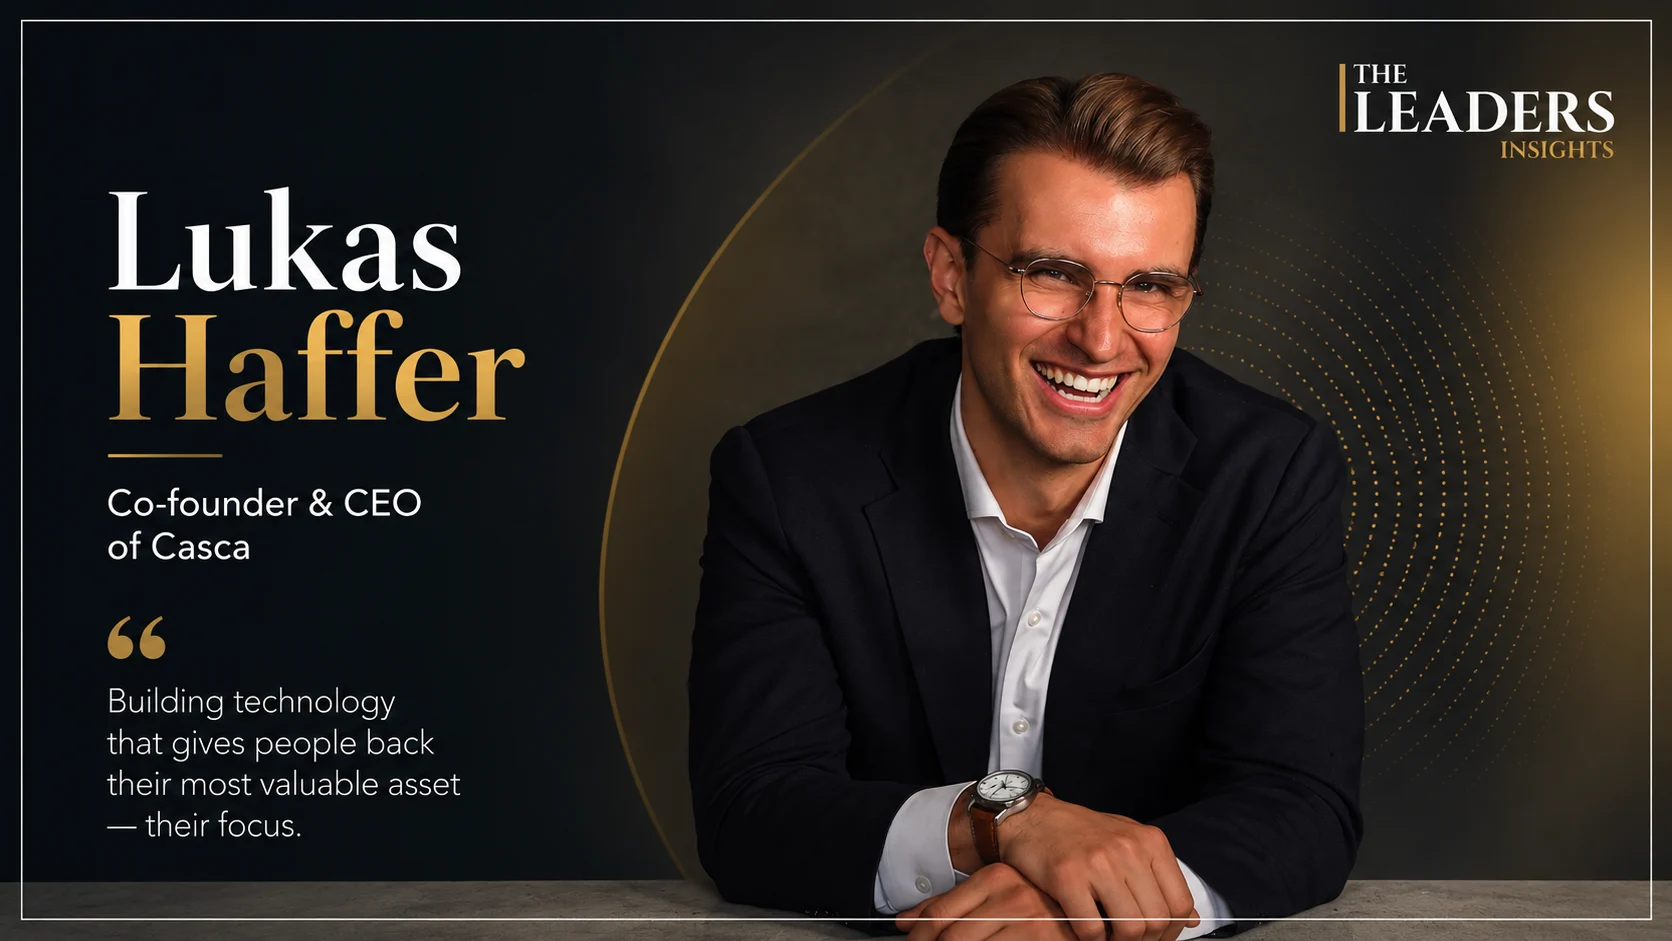
Lukas Haffer, co-founder and CEO of Casca, is using artificial intelligence to simplify this work. Casca develops an AI-based loan origination platform for banks and other financial institutions. Its technology is designed to help lenders process small-business and commercial loan applications more efficiently while keeping bank employees involved in important decisions.
The company’s work reflects a larger opportunity for American banks: using AI to remove administrative delays without weakening risk management, compliance, or customer trust.
From Banking Experience to an AI Startup
Haffer’s interest in modernizing banking comes from direct industry experience. Before founding Casca, he worked at Avaloq, a provider of banking software. According to Y Combinator, he served as Chief of Staff for Avaloq’s European market and spent several years working with core banking systems and operational processes.
He later completed an MBA at Stanford University (where he graduated) as an Arjay Miller Scholar. At Stanford, he met Isaiah Williams, a machine-learning engineer who became Casca’s co-founder and chief technology officer.
Williams brought technical experience in conversational AI and production machine-learning systems. Haffer contributed his understanding of banking operations, financial technology, and the problems created by older systems.
Together, they founded Cascading AI in 2023. The company now operates under the name Casca and is based in San Francisco. It participated in Y Combinator’s Summer 2023 program.
The founders focused first on lending because it combines several challenges that AI can address. Applications contain structured details, written explanations, financial statements, tax documents, and ongoing communication between borrowers and bank employees. Much of this information has traditionally been reviewed and organized manually.
Why Small-Business Lending Needs a Better Process
Banks have a strong reason to serve small businesses. Lending can create long-term relationships that may later include deposit accounts, payment services, credit cards, and other financial products.
However, smaller commercial loans can be costly to process. A bank may need to complete many of the same administrative and compliance steps required for a larger loan, while earning less revenue from the transaction.
This creates an operational challenge. If the process takes too much staff time, banks may find it difficult to serve a high volume of smaller applicants. Business owners may then look for faster alternatives, including online lenders that sometimes charge higher rates.
Delays can also cause qualified applicants to abandon the process. An owner managing employees, customers, inventory, and cash flow may not have time to respond to several emails asking for different documents.
How can banks speed up lending decisions without compromising their standards? Casca’s approach is to use AI for repetitive work while allowing trained banking professionals to retain control over credit policies and final decisions.
How Casca Supports the Loan Application Process
Casca describes its product as an AI-native loan origination system. The platform is designed to manage several stages of small-business and commercial lending within a connected process.
Its AI loan assistant guides applicants through the process by explaining which documents are required, requesting missing information, and following up on incomplete applications. This gives business owners clear support while reducing routine work for bank employees.
The system can also read financial documents and organize information for review. Instead of manually moving data from PDFs, emails, and spreadsheets, lending teams can receive the details in a more structured format.
Casca says its technology can support tasks such as:
- – Guiding applicants through the loan process
- – Collecting required business documents
- – Checking applications for missing information
- – Reading and organizing financial records
- – Communicating with applicants by email or text
- – Preparing information for credit review
- – Helping employees create credit memos
- – Tracking applications through different stages
These functions do not remove the need for bankers, underwriters, or credit officers. They are intended to give those professionals more time for financial analysis, risk evaluation, customer discussions, and final decisions.
Giving Bank Employees More Time for Customers
One of Haffer’s central ideas is that automation should make banking employees more productive rather than remove them from the relationship.
Loan officers often spend a large part of their day requesting documents, checking files, entering information, and answering basic process questions. These tasks are necessary, but they do not always require the judgment and relationship skills of an experienced banker.
When AI handles part of the administrative work, employees can spend more time understanding the business behind an application. They can discuss how the company earns revenue, why it needs financing, how the owner plans to use the funds, and what risks may affect repayment.
This human interaction remains valuable in small-business banking. Unlike a standard consumer purchase, a commercial loan may involve seasonal revenue, unusual expenses, industry-specific risks, or a growth plan that requires explanation.
AI can help organize the information, but a banker provides context and judgment.
For CEOs and managing directors, this creates a useful way to think about automation. The goal should not be to add AI to every task. It should be to identify work that slows employees down and prevents them from serving customers.
Early Work With Bankwell Bank
Bankwell Bank, a Connecticut-based financial institution, was an early Casca customer. The bank used Casca’s platform for small-business loan applications and later became an investor in the company.
At FinovateSpring 2024, Casca reported that the Bankwell implementation had processed hundreds of applications ranging from $10,000 to $5 million. The company also reported improvements in application completion and manual workload.
These performance figures came from Casca’s own presentation and should be understood as results from a specific customer implementation, not a guarantee for every financial institution.
Still, the relationship offers an important lesson. Banks may be more willing to adopt AI when a technology provider solves a clearly defined operational problem and can work within existing processes.
Casca has since been associated with additional financial institutions, including Live Oak Bank and Huntington National Bank. In August 2025, the company raised a $29 million Series A round led by Canapi Ventures. Axios reported that the investors included Live Oak Bank, Huntington, Bankwell, Y Combinator, Peterson Ventures, and Alliance Funding Group.
Investment from banking organizations can provide more than capital. It may give a fintech company a closer understanding of lender requirements, implementation challenges, and regulatory expectations.
Working With Existing Bank Systems
Replacing a bank’s main technology infrastructure can be expensive, risky, and time-consuming. Many financial institutions therefore prefer tools that can work with the systems they already use.
Casca says its AI agents are designed to connect with existing banking infrastructure through application programming interfaces and other technical methods. The company also uses computer vision to read documents and work with information that may not already exist in a structured format.
This approach matters because loan applications rarely arrive as clean, standardized data. A single file may contain tax returns, bank statements, ownership records, business plans, and written explanations.
AI can help extract and organize this information. However, banks still need strong controls to check accuracy, manage access, protect confidential data, and respond when the system produces an uncertain or incorrect result.
An effective implementation should make the process easier to review, not create a new system that employees cannot understand.
Compliance Cannot Be an Afterthought
Speed is valuable, but lending decisions must remain fair, explainable, and consistent with the law.
Banks must follow the same laws and internal policies whether lending decisions are made by employees or supported by AI. These include requirements for fair lending, customer privacy, data security, and credit approval.
The Consumer Financial Protection Bureau has stated that lenders using complex algorithms must provide applicants with accurate and specific reasons when taking adverse action. A bank cannot use AI as an excuse for providing an unclear explanation when credit is denied or offered on less favorable terms.
This makes human oversight important. Financial institutions need to understand:
- – What information an AI system uses
- – How the output affects the lending process
- – Who reviews recommendations and exceptions
- – How errors are identified and corrected
- – Whether results are tested for unfair differences
- – How decisions and communications are documented
- – What happens when the model or workflow changes
Casca describes its system as using a human-in-the-loop approach. In practice, the quality of that oversight depends on how each bank configures the platform and assigns responsibility.
For bank leaders, responsible AI requires more than buying secure software. It requires clear governance, employee training, ongoing testing, and senior management accountability.
A Better Experience for Small-Business Owners
The most visible benefit for borrowers may be a simpler application.
An AI assistant can remain available outside normal banking hours, remind an applicant about missing documents, and answer routine process questions. This can help an owner continue an application without waiting for a loan officer to return a call.
Faster communication may also reduce uncertainty. Applicants want to know what information is required, whether their documents were received, and what will happen next.
Yet automation should not make the experience impersonal. Business owners should be able to reach a qualified employee when they need advice, want to explain unusual circumstances, or disagree with information in their application.
The strongest customer experience combines digital convenience with access to a real person.
What Business Leaders Can Learn From Haffer’s Approach
Casca’s development offers several lessons for CEOs and founders considering AI within regulated industries.
First, identify a recurring problem that costs the bank significant time or money. Haffer and Williams did not start with a general AI product for every banking function. They focused on loan origination, where document collection and communication create clear delays.
Second, build around existing professional expertise. Casca is designed to support lending teams, not replace the people responsible for making important credit decisions. This can make adoption easier and reduce the risk of losing important institutional knowledge.
Third, design compliance into the workflow. In banking, healthcare, insurance, and other regulated sectors, responsible automation must include review controls, records, data protection, and clear accountability.
Finally, measure the complete customer journey. Processing one document faster is useful, but the larger goal is to reduce the time between a business owner starting an application and receiving a well-supported decision.
The Future of AI in American Banking
AI will not remove the complexity of business lending. Banks must still confirm that borrowers can repay their loans, manage lending risks, follow regulations, and approve credit responsibly.
What AI can change is the amount of manual effort required to move an application through the process.
Lukas Haffer’s work at Casca shows how a focused technology company can approach a long-standing banking problem. By combining conversational AI, document processing, workflow automation, and human review, Casca aims to help banks serve more small businesses without placing the full burden on lending teams.
For American banks, the opportunity is larger than faster processing. A well-designed system can create more time for customer relationships, help employees focus on higher-value work, and make traditional bank financing more accessible to business owners.
The leaders who succeed with AI will be those who balance speed with responsibility. Technology may organize documents and workflow, but trust, judgment, and accountability must remain firmly in human hands.